It's the third day of the new month. You're still matching last month's PayPal payouts, trying to decide which Stripe fees belong to which client, and searching through email for an invoice your accountant needs. The books aren't technically impossible, but every missing receipt and unexplained deposit turns a routine task into a late-night reconstruction.
A month end close checklist prevents that scramble by creating a repeatable process for finalizing transactions, reconciling accounts, posting adjustments, and reviewing financial statements. For freelancers and small teams, the checklist works best when it manages data readiness and owner handoffs, not just task order. If the information arriving at month-end is incomplete, a beautifully sequenced list won't make the close faster.
What a Month End Close Is and Why It Trips Up Small Teams
A month-end close brings one reporting period to a controlled finish. You confirm that transactions belong in the correct period, reconcile the books with bank and payment records, record necessary adjustments, and review the profit and loss statement and balance sheet before locking the period.
The work looks simple on paper. In a small business, income and expenses may pass through a bank account, card, payment processor, invoicing system, or an account that was never meant for business spending. One person may enter transactions, approve payments, answer questions, and review reports. Without a clear owner handoff, errors can remain hidden until the final review.
Practical rule: A checklist cannot repair missing source data. It can make missing data visible sooner.
Where the process breaks
Recurring problems usually come from weak timing and ownership controls:
- Wrong-period posting: A payment received on the first day of the new month is recorded in the previous month, or a late invoice is left out of the period it belongs to.
- Mixed accounts: Personal and business transactions share a feed, forcing the owner to reconstruct business activity during the close.
- Deferred expenses: Annual subscriptions, retainers, or prepaid services are expensed in full instead of recognized across the periods they cover.
- Missing cutoff: No one sets a clear point for invoices, expenses, contractor payments, and receipts to stop entering the current period.
- Unclear ownership: A bookkeeper waits for the owner to explain a transaction, while the owner expects the bookkeeper to identify it independently.
These gaps distort decisions. Revenue may appear stronger or weaker than it was, expenses may fall into the wrong month, and cash reports lose value. Findings reported in FloQast's month-end close survey show why repeatable controls matter: more than 82% of accounting professionals said the close affected them personally, only 1 in 4 felt very confident that their last close was error free, and 3 out of 4 had reopened the books after closing to correct errors.
For a freelancer, the practical fix is a process that moves transaction capture, coding, and questions earlier. Recurring categorization, receipt collection, and owner answers should happen during the month. Month-end can then focus on reconciliation, judgment, and review instead of cleanup. The checklist becomes a short control layer, with the owner responsible for timely answers and the bookkeeper responsible for clear follow-up.
Pre-Close Prep That Makes Month-End Boring
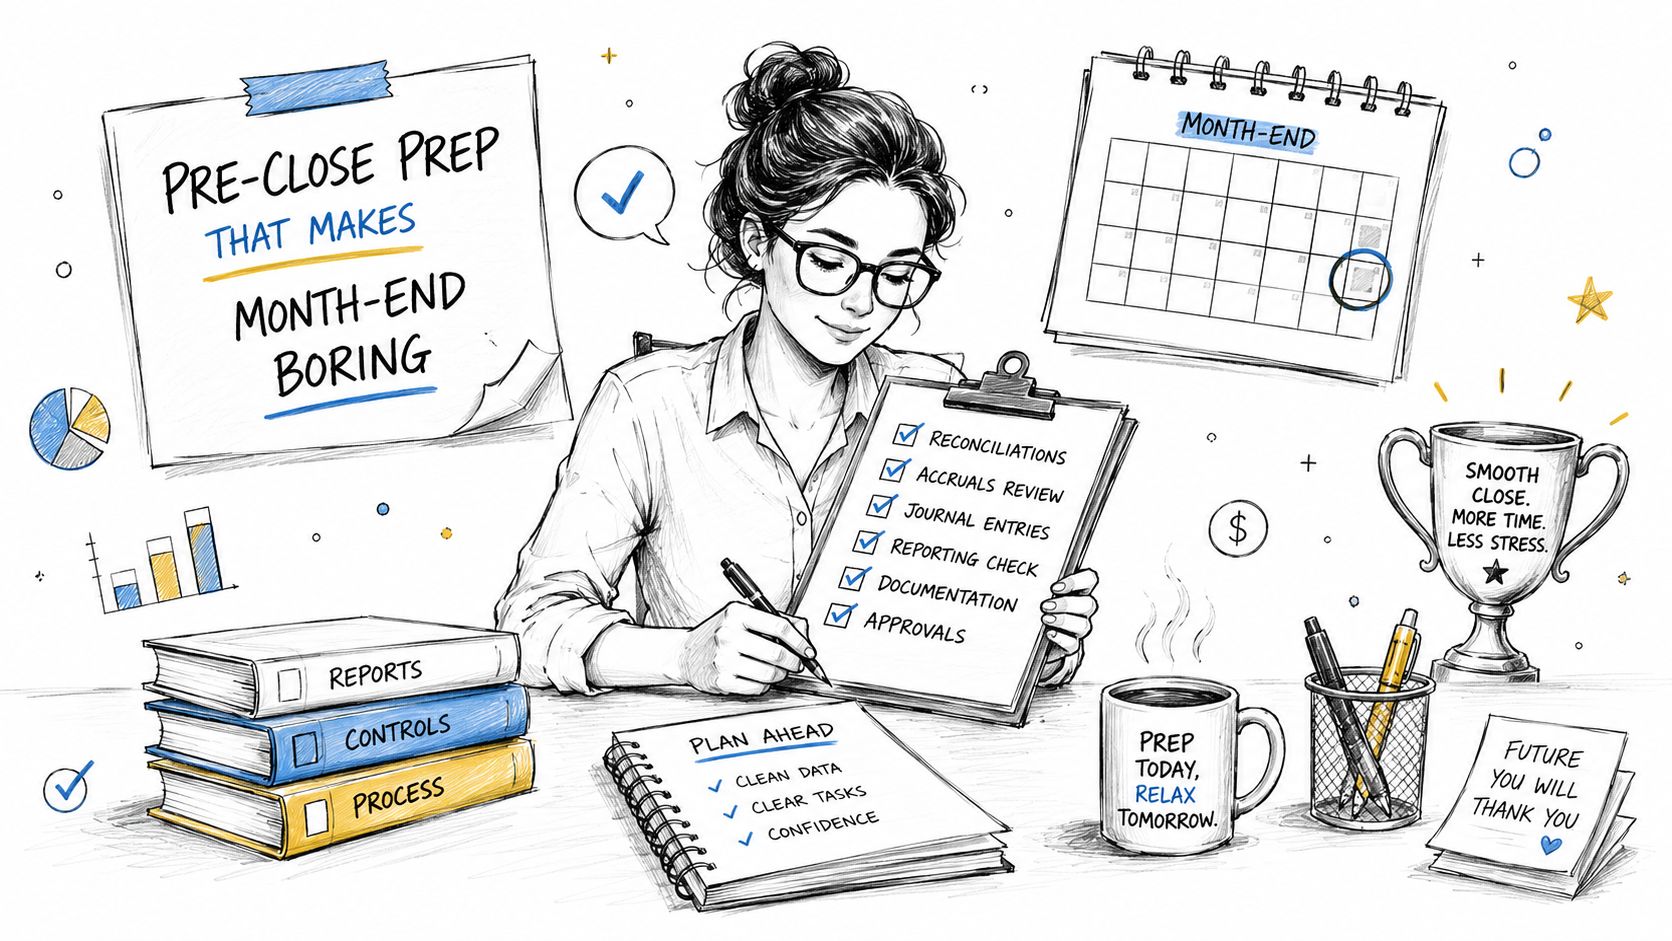
The easiest close is built before the last day of the month. Daily and weekly preparation keeps the ledger current, gives the owner time to answer questions, and stops the final review from becoming a search through old messages.
A useful starting point is a consistent account structure. If categories are vague or duplicated, transaction coding becomes subjective and reports lose meaning. Steingard Financial's explanation of a chart of accounts can help a small operator understand how revenue, expenses, assets, liabilities, and equity should be organized.
Five habits that protect the close
Capture receipts when transactions post. Upload the receipt or add a note the same day. If a client lunch has no documentation by Friday, don't expect to remember its business purpose at month-end.
Reconcile the business card and payment accounts within 48 hours. A recent payment processor deposit is easier to match while the related invoices and fee reports are still easy to find. Use the same discipline for the business card, especially when several employees or contractors can charge it.
Tag bank lines before the weekend. Assign each transaction to a client, project, location, or internal category while the context is fresh. A $1,200 software subscription shared across three client projects should use a documented allocation rule, rather than a guess made on the last day of the month.
Run a weekly P&L flash report every Friday. The report doesn't need to be final. It should expose missing revenue, unusual expenses, and categories that need an owner decision.
Lock the prior week by Tuesday of the next week. Review open questions, post corrections, and prevent old transactions from remaining indefinitely unresolved. This creates a rolling cutoff without waiting for month-end.
Before the month-end window begins, confirm that bank feeds are matched to the penny, uncategorized transactions are below 1% of total transaction volume, and all material invoices have been issued. Those conditions form a useful readiness gate, not a universal accounting rule. If one isn't true, assign an owner and a deadline before starting the final close.
For a broader explanation of recurring bookkeeping tasks, use the monthly bookkeeping guide. The point is simple: boring month-ends are created during the month, through timely inputs and clear handoffs, not through heroic cleanup at the end.
The Step-by-Step Month End Close Checklist
A freelancer or two-person office should treat the close as one controlled workflow. The sequence below starts with period boundaries and cash, moves through adjustments and reconciliations, and ends with a human review of the statements.
| Block | Step | Owner | Output |
|---|---|---|---|
| Cutoff and cash | Set the period cutoff and lock the accounting period | Bookkeeper or owner | Locked reporting period |
| Cutoff and cash | Pull bank and card statements through the last business day | Bookkeeper | Saved statements |
| Cutoff and cash | Confirm material receipts, invoices, payments, and deposits have posted | Bookkeeper | Completeness note |
| Accruals and adjustments | Review unpaid bills, earned revenue, prepaid costs, and recurring entries | Bookkeeper | Adjustment list |
| Accruals and adjustments | Post and document accruals, deferrals, amortization, and reversals | Bookkeeper | Approved journal entries |
| Reconciliations | Reconcile bank, cards, processors, loans, payroll, and contractor payments | Bookkeeper | Reconciliation workpapers |
| Statement review | Review P&L and balance sheet against prior month and budget | Owner or reviewer | Variance explanations |
| Sign-off | Record date, reviewer initials, and unusual-item note | Owner or reviewer | Completed close record |
Block one covers cutoff and cash
Choose the last business day included in the period. Lock the period in the accounting system, or restrict backdated entries if the system supports that control. Then save the bank and credit-card statements ending on that date.
Confirm that material receipts have posted. If a client paid through a processor but the deposit hasn't reached the bank, trace the processor balance and fee detail rather than treating the missing bank deposit as unexplained revenue. Late invoices, missing expense receipts, and uncleared transfers belong on an exception list with a named owner.
Block two handles adjustments
Review unpaid bills and services received but not yet invoiced. Record accruals where the expense belongs in the closed period, then document the basis for each entry. Review prepaid items, deferred revenue, recurring entries, and amortization schedules as applicable to the business.
Keep adjustment entries explainable. A short description should identify the period, account, amount, and reversal or follow-up needed. This is also where you correct a recurring classification problem instead of carrying it forward.
Block three proves the balances
Run each reconciliation against an independent record:
- Bank accounts: Match the ledger to the statement ending balance.
- Credit cards: Match charges, payments, and the statement balance.
- Stripe and PayPal: Match aggregate balances and fees to merchant reports.
- Loans: Match principal, interest, and ending balance to the amortization schedule.
- Payroll and contractors: Match payments to the payroll or contractor journal.
A bank statement reconciliation explanation is useful when a new owner needs to understand why matching the ending balance isn't enough. Each difference needs a documented explanation, whether it's a timing item, an unposted charge, a duplicate, or an error.
Smart Receipts' 8-step financial close guide offers another reference point for organizing close activities, but a small team should adapt any template to its actual accounts and handoffs.
Block four requires judgment
Read the P&L and balance sheet line by line. Compare the current month with the prior month and with budget, then investigate every variance above 5% before marking the period closed. The percentage is a review trigger, not proof that an entry is wrong. A large variance may be correct, while a smaller unexplained change may deserve attention.
Finish with a sign-off line containing the close date, reviewer initials, and one sentence about any unusual item. If the owner is also the bookkeeper, the review still matters. Step away from data entry and read the reports as a business owner.
Benchmarks and Where Small Businesses Get Stuck
Close time is measurable, but the number of hours alone doesn't explain the delay. A short close can still contain errors, while a longer close may reflect a complex transaction flow. The useful question is where the hours are going and which checklist control should have caught the issue earlier.
The benchmark ranges supplied for small teams put a one-person freelancer close at 2 to 6 hours, a 5 to 10 person team at 8 to 20 hours, and a 20-person team at 25 to 60 hours. Bank reconciliation can consume 30% to 40% of that window. These operating ranges are best used for self-diagnosis rather than as promises.
| Team Size | Total Close Hours | Bank Reconciliation | Journal Entries | Statement Review | Typical Close Day |
|---|---|---|---|---|---|
| One-person freelancer | 2 to 6 | 30% to 40% | Remaining close work | Final review | Day 3 to day 5 |
| 5 to 10 people | 8 to 20 | 30% to 40% | Remaining close work | Final review | Day 5 to day 7 |
| 20 people | 25 to 60 | 30% to 40% | Remaining close work | Final review | Day 7 to day 10 |
The wider benchmark picture shows why many teams feel stuck. One benchmark reports a 6.4-day median close across 2,300 organizations, with the fastest 25% closing in 4.8 days or less and the slowest 25% requiring 10 or more days. Another APQC-based benchmark places the median between 6.0 and 6.4 calendar days, with top-quartile teams at 4.8 days or less and bottom-quartile teams at 10 or more days, as described in month-end close benchmark guidance.
Match the bottleneck to the missed control
- Unreconciled PayPal or Stripe payouts belong in the processor reconciliation step, but the underlying prevention is a more frequent review during the month.
- Misclassified contractor expenses point to weak coding rules and missing owner handoffs before the journal-entry review.
- Prepaid amortization belongs in the adjustments block and should be driven by a standing schedule.
- Unpaid invoices and expenses require a cutoff review, followed by documented accrual decisions.
- Sales tax needs a recurring calculation and filing-readiness check, not a last-minute estimate.
Recent benchmark reporting says 50% of finance teams take 6 or more business days, only 18% close in 1 to 3 business days, and 27% need more than 7 business days. The same reporting identifies cash reconciliation as the most time-consuming activity, supporting the emphasis on daily bank review and clear account ownership in the 2025 close benchmark discussion.
A late close leaves invoices waiting, cash visibility stale, and tax preparation more expensive. Before changing software, ask: Which account or handoff was open longest, and what evidence would have exposed it a week earlier?
Automation, Internal Controls, and Ready-to-Use Templates
Automation should remove repetitive handling, not remove judgment. A sensible control framework gives each task an owner, routes exceptions to a reviewer, and preserves enough documentation to explain how a balance was reached.
Build controls around the people involved
If a bookkeeper prepares the close, the owner should review unusual transactions and approve the final statements. When one person does everything, use a deliberate second-look routine, even if the reviewer is only checking reconciliations, adjustments, and variance explanations.
For larger purchases or unusual payments, set a dual-approval threshold that fits the business's risk tolerance. The exact threshold belongs in the written policy. What matters is that the rule is decided before a questionable payment arrives, not invented after the fact.
Monthly variance review should compare the current P&L and balance sheet with the prior month and budget. Save explanations with the close workpapers, especially for unusual expense categories and old outstanding receivables.
Automate the repetitive layer first
Start with bank feeds, recurring journal entries, sales-tax calculations, and contractor tracking. These activities follow recognizable rules and can reduce repeated entry when the underlying data is reliable.
Keep a person responsible for reviewing unusual expense categories, investigating old receivables, checking failed imports, and approving adjustments. Automation can propose a match or classification, but it can't determine whether a payment represents a valid business purpose without context.
Accounting platforms differ in how they support bank-rule customization and multi-user approval workflows. Compare those specific capabilities against your process rather than choosing on brand familiarity. If you need a directory of finance tools and bookkeeping resources, BookkeepDIY's financial close software guide can be used as a starting point for evaluating relevant categories.
Two simple templates
A one-page Excel checklist should include:
- Task: The exact action, such as “match processor report to deposits.”
- Owner: One named person, not a department.
- Due date: The date the task must be completed.
- Status: Not started, in progress, blocked, or complete.
- Evidence link: The statement, report, or workpaper supporting completion.
- Reviewer note: The exception and its resolution.
A Google Sheets version can use the same columns with conditional formatting. Flag any row that isn't marked complete by day 5, then add a blocker column so the owner can explain whether the delay comes from missing data, a pending approval, or a reconciliation difference.
The checklist is the visible layer. The control is the handoff behind each row.
From Monthly Checklist to Continuous Close
The objective isn't merely to finish month-end faster. It's to make month-end shorter by moving routine work into a steady rhythm, so the final review doesn't become a data-cleanup marathon.
A freelancer can use a 5 to 15 minute daily routine:
- Review the prior day's bank-feed activity.
- Code new transactions and attach receipts.
- Add unusual items to a running note for the bookkeeper or future review.
Update the contractor log every time a vendor is paid instead of reconstructing the year during tax preparation. Reconcile high-activity accounts weekly, chase missing invoices while the work is still recent, and record recurring adjustments on a schedule.
A continuous close doesn't mean reviewing every report every day. It means preventing predictable cleanup from waiting for the calendar to turn.
For a freelancer, a true continuous close may be a 30-minute review on the first business day of each month. By then, the owner checks the exception note, confirms the key reconciliations, reviews statements, and signs off. The process stays manageable when three behaviors become essential:
- Weekly reconciliation: Match active accounts before discrepancies become historical puzzles.
- Same-day coding: Capture the business purpose while the transaction still makes sense.
- Fixed monthly review time: Reserve the review block on the calendar so it doesn't slide into the next reporting period.
Recent guidance points toward this shift. Gartner reported that 86% of finance functions wanted a faster real-time close, 68% wanted a cheaper close, and 64% wanted an error-free close by 2025, as stated in its finance survey announcement. For a small business, that doesn't require an elaborate finance department. It means using the month-end checklist as a control-and-review layer, while the recurring data work happens earlier.
BookkeepDIY helps freelancers and small teams evaluate bookkeeping tools, understand accounting terms, and organize finance back-office workflows such as month-end close. Visit BookkeepDIY to compare relevant resources and build a close process that fits the way your business operates.